Free. Your numbers are saved to your account and never shared. By creating an account you agree to our Privacy Policy.
The Home Plan
Your retirement, with a home and without
This is your retirement plan, worked out twice: once renting for life, and once owning a home that’s paid off by the time you retire. See how much each one needs you to invest, starting today.
Will that last?
CPP and OAS are not included. What you get depends on how long you have lived and worked in Canada, and it lowers both plans by about the same amount, so the gap between renting and owning stays the same.
If you rentIf you own
🏠If you own, you also have a paid-off home that isn’t counted here.
View every year as a table
How the stress test is calculated
On the day you retire you stop adding money. What you have built is split 60% into stocks and 40% into bonds.
Stocks follow what the S&P 500 fund SPY actually did, month by month, starting from a market like February 2000 (bear case) or February 1993 (bull case). Prices only, dividends are not counted. After 2025, where the history ends, stocks grow 8% a year.
Bonds grow 2.5% a year.
Once a year you take out the gross income from your monthly bill. It rises with inflation every year.
In both cases, the first year's income comes from stocks. Every year after that, if taking it from stocks would leave them worth less than they were on the day you retired, it comes from bonds instead, so the stocks have time to recover. If the bonds cannot cover a full year, it comes from stocks.
CPP and OAS are not included.
Are you ready to buy a home?
Six questions, 100 points. The score looks at two things: whether you can carry a home, and whether buying now makes sense for you.
Watch out: this score does not look at your debts or your credit score. Both affect whether a lender approves you and at what rate, and they need a proper review of their own.
What would move your score most
How much home should you buy?
The bank tells you the most it will lend. We tell you what still leaves room for the rest of your life.
Does your life fit?
How is this calculated?
The home buying process
Eleven steps, from the first call to the keys. Click a step to see who is on your side, what happens, and what to have ready.
Before you look
1
Run your affordability numbers
YouMortgage agentBefore anything else
Talk to a mortgage agent before you look at a single listing. We run your numbers the way this tool does, but in more depth: your real life, not just what a bank would approve. Then we find your gaps. Most buyers leave free money on the table:
FHSA (First Home Savings Account). Put in up to $8,000 a year, up to $40,000 in total. You get a tax refund on what you put in, and you take it out tax-free for your first home.
RRSP Home Buyers’ Plan. Take out up to $60,000 each from your RRSPs for your first home, then pay it back over 15 years.
Use both. They work together, and a couple can each use both.
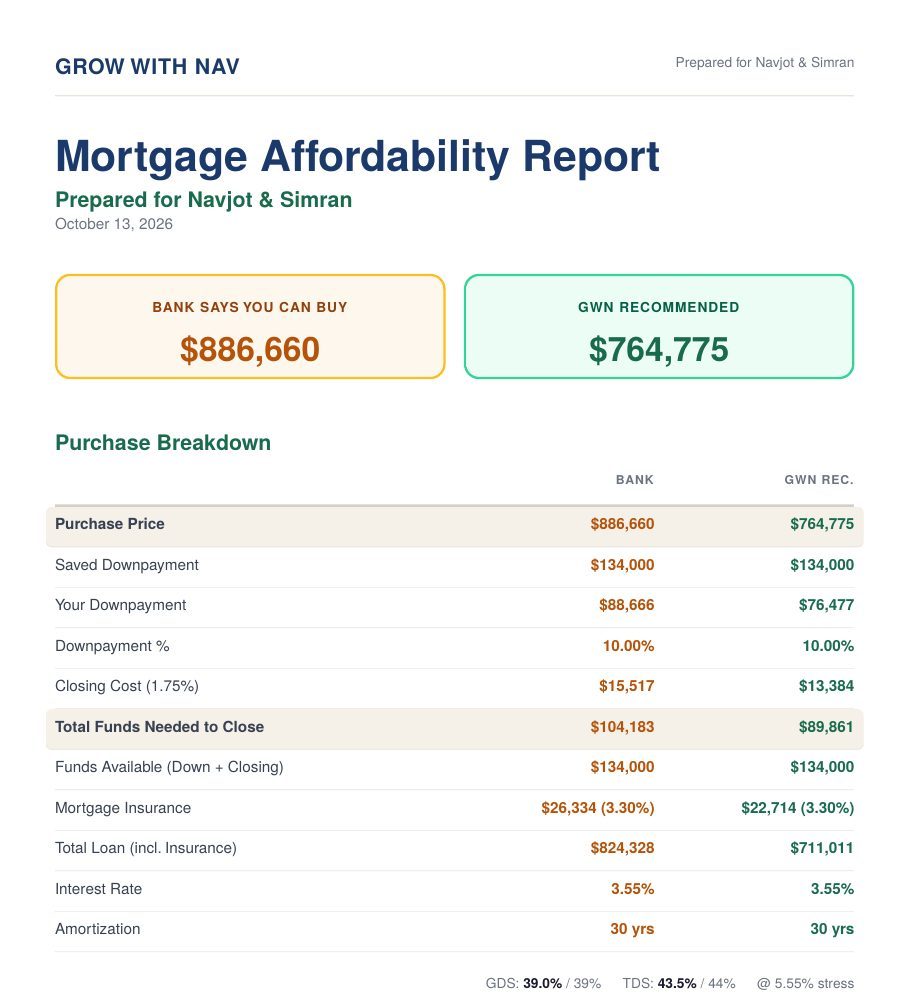
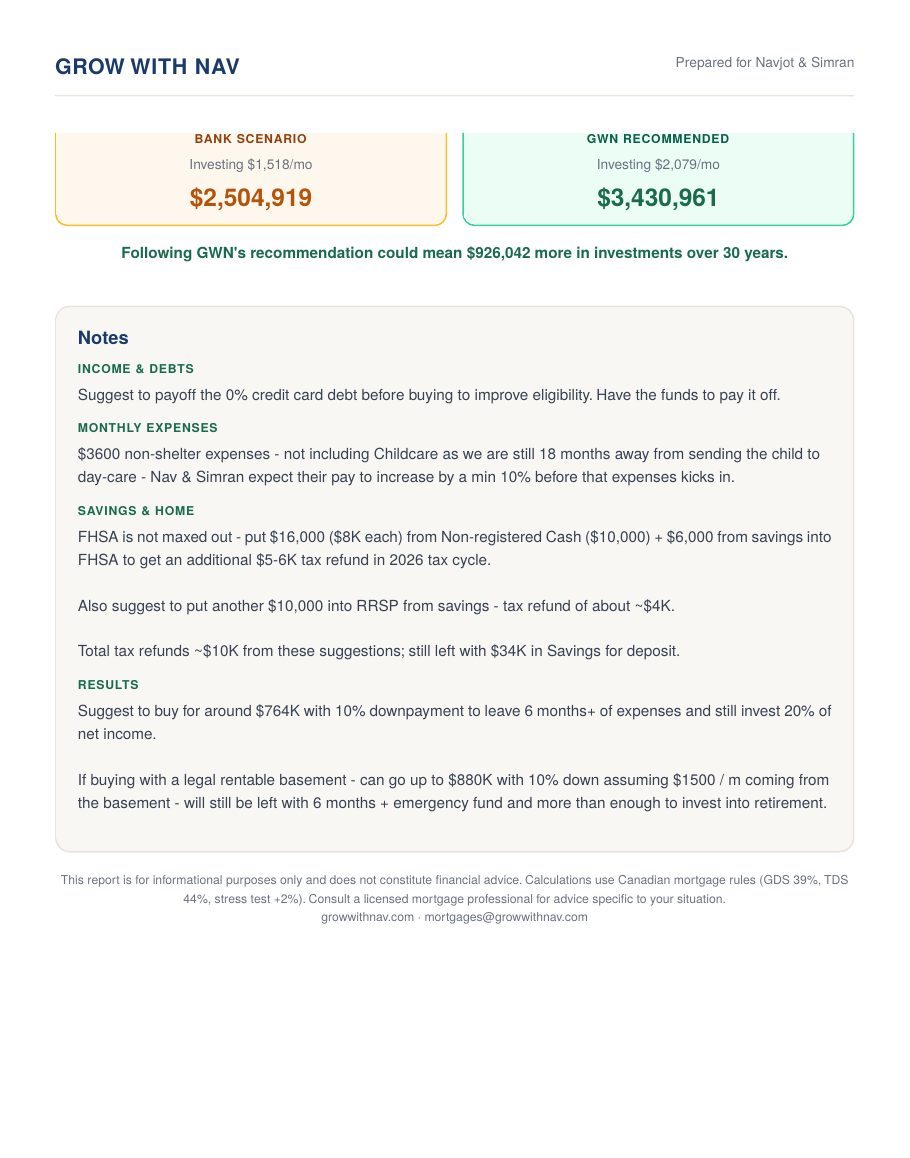
You walk away with your own mortgage report:
Your two numbers. What the bank says you can buy, next to the GWN recommended price, with your down payment, closing costs and mortgage.Your gaps. Notes written for you: money left on the table, debts to clear first, and what your investing could grow to.
Know where you want to live and what you need before you talk to a realtor. Think about your commute, schools, family nearby, and what homes cost in each area. Even if you are not sure about location yet, fill in the checklist below.
Share it with your Bricks N Dreams realtor before your discovery call.
Finding the home
3
Book a discovery call with a Bricks N Dreams realtor
YouBricks N Dreams realtor
Your realtor is the second person on your team, so choose them with care. Book a discovery call with a Bricks N Dreams realtor. Here is why our clients work with us:
Research first. Every recommendation is backed by data on the home, the street and what similar homes sold for.
Deals you can negotiate. We look past what everyone else sees on MLS: power of sale homes, delisted homes where we call the owner directly, and off-market homes. These are the deals that can be negotiated well below fair market value.
Our pay is on the line. If we can’t negotiate a better price, part of our commission comes back to you at closing: up to 1% of the price, capped at $15,000. This is the performance credit, and step 5 shows how it works.
One team with your mortgage agent. You, your Bricks N Dreams realtor and your Grow With Nav mortgage agent work in one WhatsApp group, so nothing gets dropped. We shop with your GWN recommended number from step 1, the one built around your retirement, not the most a bank will lend.
See for yourself
$30,000negotiated off the list price, on average
3.3%below list price, on average, across our 200 most recent deals
500+families helped in the last 3 years
25agents across Canada: the GTA, KWC, Calgary and BC
Top 25teams in Canada, out of 400+ in our brokerage
Known for accountability, precision and quality work. Our motto when you buy: get resale right, and everything else follows.
★★★★★180+ five-star reviews
“Working with Arka has been an absolutely wonderful experience. What started as a professional relationship quickly turned into something much more meaningful. He is incredibly honest, always available no matter the time of day, and truly attentive to every little detail throughout the process.
His negotiation skills are outstanding, and he went above and beyond not just in helping us with our purchase, but also in quickly securing a tenant for our condo. His team is equally efficient, responsive, and a pleasure to work with.
After a not-so-great experience with our previous realtor, we had lost a lot of confidence—but Arka completely changed that. He supported us every step of the way, motivated us, and made us feel comfortable and confident again. What really stood out was that he never prioritized his own profit; instead, he genuinely advised us to make decisions that would keep us financially safe.
We are truly grateful for everything he has done for us. Working with him has been a blessing, and today, he feels more like family than just a realtor. Thank you, Arka!”
Before you step into a single home, we send you every home on your shortlist side by side: what MLS, the photos and our own research already tell us, from the price to the schools. This one is real: three homes in Guelph, addresses removed.
Swipe the table to see all three homes.
Home A
Home B
Home C
Price
List price
$759,900
$799,990
$800,000
Offers
Anytime
Anytime
Anytime
Schools
Designated elementary school
Westwood PS
Westwood PS
Westminster Woods PS
School rating (Fraser 2025)
8.0/10 #351 of 3,052
8.0/10 #351 of 3,052
8.7/10 #161 of 3,052
Distance to school
0.8 km
0.9 km
1.1 km
Location
Area
Willow West
Willow West
Westminster Woods
Distance to GO station
5.1 km
5.2 km
7.8 km
Nearest park
400 m walk
150 m walk
100 m walk
Facing
West
West
East
The home
Type
Detached, 2-storey
Detached, 2-storey
Detached, 2-storey
Ownership
Freehold
Freehold
Freehold, with a POTL fee
Year built
1986
1987
2004
Bedrooms
4
4
3
Bathrooms
4
3
3
Square feet
1,634
1,620
1,703
Parking
2 garage, 2 outside
1 garage, 4 outside
1 garage, 1 outside
Basement
Finished
Partly finished
Unfinished
Remarks
Mature lot, double garage, two living areas
Main-floor bedroom with ensuite, huge backyard, immediate possession
No rear neighbours, vaulted primary bedroom with ensuite
More than the house. The school your kids would go to, how it ranks in Ontario, how far it is, and the commute, before you book a showing.
Showings that count. You walk in already knowing the home, so the visit is about what the listing can’t tell you.
One shared list. It lives in your WhatsApp group. Send any home you like and we check it the same way.
See homes in person with your Bricks N Dreams realtor. Right after the showings, we send you a showings report, so you decide with facts, not fading memories.
What’s in your showings report
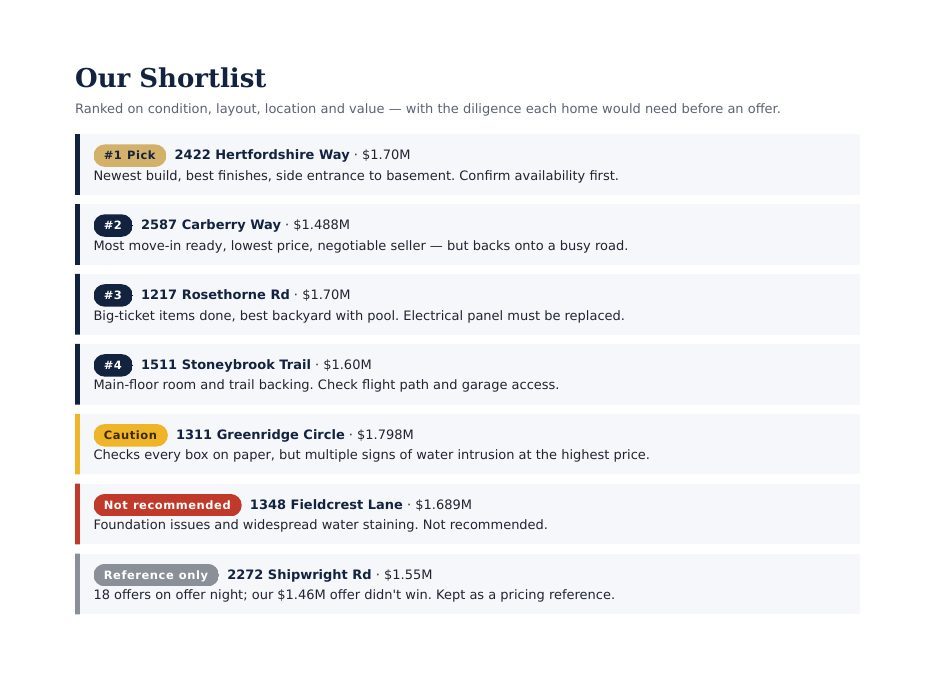
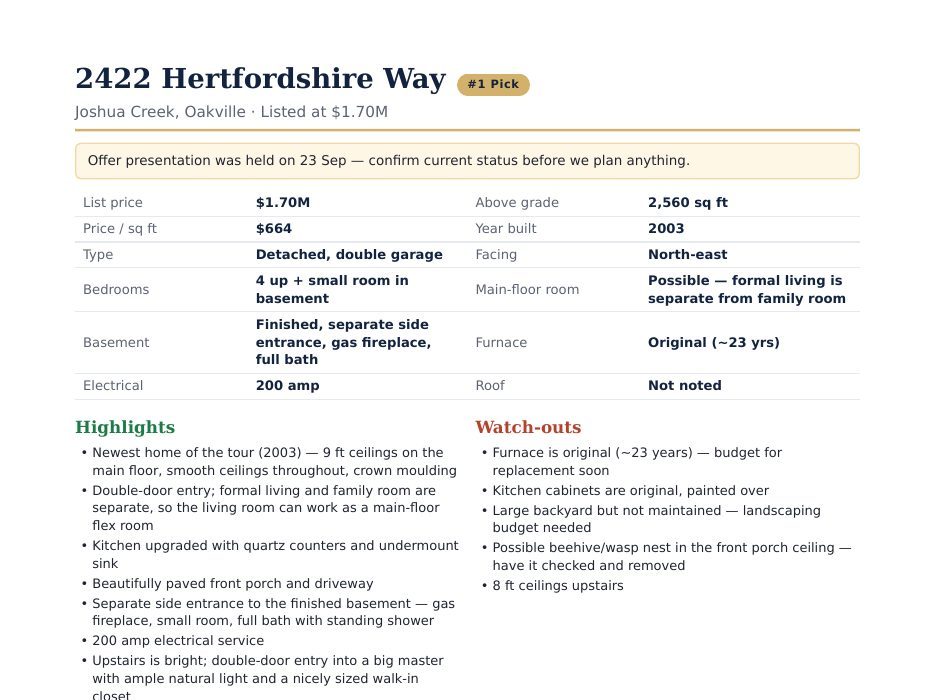
A ranked shortlist. Every home ranked on condition, layout, location and value, from our #1 pick to the ones we would walk away from.
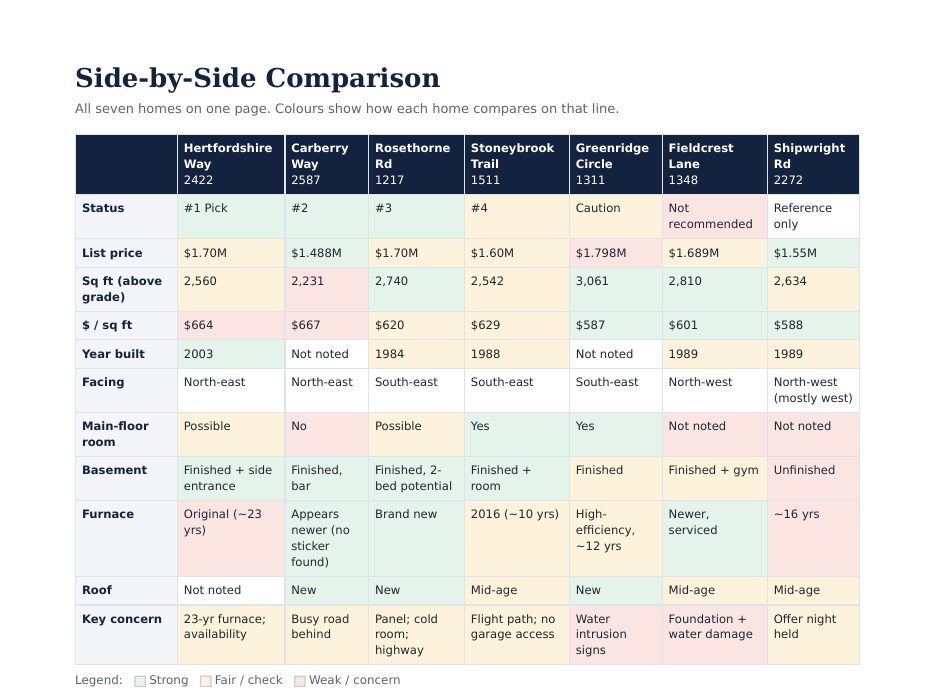
Every home side by side. One page, colour-coded: strong, fair, or a concern.
Highlights and watch-outs. Home by home, from the age of the furnace to signs of water getting in.
Our honest take. A clear recommendation on every home, as if we were buying it ourselves.
Open items. Everything to confirm before an offer, and the next steps.
The shortlist, ranked.Side by side, colour-coded.Every home, with our take.
When you find the one, your Bricks N Dreams realtor first talks to your Grow With Nav mortgage agent, so the offer is in line with your numbers for that property. Then we write the offer. The performance credit is built into this step. If we can’t beat the market, our commission is on the line.
What goes in an offer: the offer price, the deposit, the closing date and a few conditions, usually a financing condition and an inspection condition. Steps 6 to 8 explain the deposit, the conditions and going firm in detail.
Negotiation is what we do best
Up to 1% back at closing
We have negotiated about $30,000 off the list price on average, across our last 200 deals. If we can’t get you a good price, part of our commission comes back to you in the form of a performance credit.
Part of our commission comes back to you at closing, in two parts.
Negotiation
What you pay, compared to the list price
3% or more under list
None
Within 3% of list
0.25%
3% or more over list
0.5%
Buy 3% or more under list and you have already won.
Time to buy
From your first showing to an accepted offer
45 days or less
0.5%
More than 45 days
None
Up to 1% of the purchase price, capped at $15,000, credited to you at closing. It does not apply to pre-construction or off-market homes.
Two examples
Under list, fast
List price
$880,000
Purchase price, 2.5% under list
$858,000
Negotiation: within 3% of list
0.25%
Time to buy: 45 days or less
0.5%
Back to you at closing 0.75% of $858,000$6,435
Over list, 60 days
List price, underlisted
$899,000
Purchase price, 5.7% over list
$950,000
Negotiation: 3% or more over list
0.5%
Time to buy: 60 days
None
Back to you at closing 0.5% of $950,000$4,750
Credits are calculated on the final purchase price. Illustrative examples only.
From offer to firm
6
Pay the deposit
YouUsually within 24 hours
The deposit is not extra money. It is part of your down payment, paid early. It is held in trust by the seller’s brokerage, not handed to the seller.
Down payment$100,000
=
Deposit now$25,000
+
Rest at closing$75,000
Closing costs are paid on top of the down payment, at the end (step 11).
7
The conditional period
YouBricks N Dreams realtorMortgage agentInspectorLawyer
Your offer can have up to four conditions. They run at the same time, and the deal only becomes final once they are met.
Financing
Sahil from our team compares lenders with you: the rate, the prepayment options and the term. The lowest rate is not always the best mortgage.
Inspection
Usually $300 to $600. The inspector checks the roof, structure and foundation, grading and drainage, the basement for moisture, plumbing, the electrical panel and wiring, the furnace, air conditioning and water heater, windows and doors, attic insulation and ventilation, and signs of pests or mould.
Status certificate (condos)
A review of the condo corporation: how healthy the reserve fund is, any special assessments, planned fee increases, lawsuits, insurance, and rules on pets and rentals. Any red flags show up here.
Lawyer review
For a power of sale, a pre-construction purchase or an assignment sale, a real estate lawyer reviews the agreement before you commit.
8
Go firm, or walk away
YouBricks N Dreams realtor
When the conditional period ends, you have two options.
Option 1
Go firm
Every condition is met and you are happy with what you found. You remove the conditions, and the deal goes firm.
Option 2
Walk away
Something doesn’t check out. You and the sellers sign a mutual release, and your deposit usually comes back in three to seven banking days.
To closing
9
Financing and documents
YouMortgage agentUsually 3 to 4 weeks
The lender finishes its checks well within the timeline. From accepted offer to closing, we recommend allowing four weeks. Have these ready:
Income: employment letter, recent pay stubs, T4s and notices of assessment
Identification: photo ID, and your PR card if you have one
Credit: your credit report, or other proof of credit if you are new to Canada
Down payment: 90 days of bank statements that show where the money came from
The home: the agreement of purchase and sale, the MLS listing and the appraisal
No big changes until you close: don’t change jobs, open new credit or make big purchases.
10
Buyer visits
YouBricks N Dreams realtorUsually two visits
First visit: bring family to see the home, measure for furniture, or let your contractor plan renovations.
Final visit: 24 to 72 hours before closing, to make sure everything is as agreed.
11
Sign with your lawyer
YouLawyerA few days before closing
You sign the final paperwork and pay the rest of your down payment plus your closing costs. Closing costs usually come to 1.5% to 2% of the price: land transfer tax (less any first-time buyer rebate), legal fees, title insurance, and adjustments for property tax or utilities the seller already paid.
Your closing costs
This is an estimate, not your closing cost. It shows roughly how closing costs add up. Yours can be very different depending on the area and municipality you buy in, the home you choose, your down payment, your lawyer and your lender.
There is nothing left for you to do. Your lawyer registers the home in your name and you get the keys. Congratulations, you are a homeowner.
Build your financial plan with Navjot
A mortgage takes about 45 days. Your financial life takes about 30 years. Parts 1 to 4 put your home inside your plan. Grow Nation is where we build the whole plan with you, starting with a financial plan made for your family.
What you get
A typical mortgage
A rate and a closing date
Two or three calls
A renewal letter in five years
No check on whether the home fits your plan
The rest, you figure out alone
A mortgage with Grow With Nav
Every lender shopped for your file
A realistic number, not just the bank’s number
One team for the whole process: mortgage agent, realtor, lawyer, inspector, renovator and more
A 1:1 financial plan with Navjot, and Grow Nation membership, included
Strategies most agents never raise, like the Smith Manoeuvre and paying off your mortgage early versus investing
Support at renewal and beyond
Your 1:1 financial plan
How your plan is built
The same engine behind part 1, run on your real numbers, with Navjot, one on one.
1
Where you are today
Your income and your monthly budget, line by line.
2
Your retirement number
What you will spend each month in retirement, grown for inflation and grossed up for tax.
3
Your assets and liabilities
Everything you own and owe on one page, and whether real estate belongs in your plan or stocks alone.
4
Tax-efficient investing
Where every dollar should go: TFSA, RRSP, FHSA or non-registered, and in what order. It matters most for high earners.
5
A tax-efficient meltdown
How you draw income in retirement from each account, real estate, CPP and OAS, paying as little tax as possible.
6
The stress test
The 4% rule is not a safe withdrawal rate: retire into a bad market and the money can run out. So we test your assets against real market data, the good years and the bad, up to the age of 95, not an arbitrary percentage.
7
Your mortgage-free date
Paying off your mortgage early versus investing the difference, and which one wins for you.
8
The Smith Manoeuvre
Where it fits: turning mortgage interest into a tax deduction while you invest.
9
Protection and insurance
Whether you are protected enough, so your family and your plan are safe if something happens to you.
10
Estate planning
Your will, power of attorney and beneficiaries, so everything goes where you want it to.
11
Your kids’ education
How much to put into an RESP to collect every grant.
12
Your written action plan
Written for you, with more than an hour of Navjot’s time on it alone: what to do every month, from your emergency fund and insurance to how much to invest, where, and when to raise it.
Inside Grow Nation
Everything that comes with it
Click any part to see it.
1:1 Financial Plan
Not a template. Navjot spends four to five hours or more on each family’s plan: the numbers, a one-on-one session, and a written plan with your retirement target, the tax shelters to use, and what to do every month.
Where it fits, it covers the Smith Manoeuvre, which turns mortgage interest into tax-deductible investment interest. Your mortgage has to be set up for it from day one.
Your 1:1 financial plan
Action plan
Sample plan
Today
Age
35, retiring at 60
Emergency fund
$15,000 of $42,000 needed
Investments
$60,000
Life insurance
$1 million each
Investing
Every month
$3,500
Raised every year
3%
Worth at 60
$4.55 million
Mix at 60
60% stocks, 40% bonds
Plus the Smith Manoeuvre
+$950,000 after tax
Your home
Mortgage
$600,000 over 30 years
Prepayment
$10,000 a year, rising 3%
Mortgage-free
At 53, not 65
At 60
Income needed, before tax
$141,539 a year
After tax
$8,846 a month
CPP and OAS
Not counted: a cushion
Stress test to 95
Retire in a bull market like 1993
$14 million left
Retire in a bear market like 2000
$5.2 million left
Your actions
Grow the emergency fund from $15,000 to $42,000, six months of spending with the mortgage.
Invest $3,500 a month, and raise it 3% every year.
Fill both TFSAs first, then RRSPs. Put every RRSP refund on the mortgage.
Prepay $10,000 on the mortgage every year, rising 3% a year.
Set up the Smith Manoeuvre on the mortgage. It unlocks about $950,000 more in after-tax net worth, on top of the $4.55 million.
Skip the rental property you were planning to buy. Your plan works without it, so there is no need to take on the extra debt, risk and work.
Keep $1 million of term life insurance each until the mortgage is gone.
Add $150,000 of critical illness coverage each. Disability is covered through your employers.
Write wills and powers of attorney, and name a beneficiary on every account.
Put $2,500 a year into your child’s RESP to collect the full $500 grant.
Meet once a year to review the plan.
A one-page snapshot. The full plan behind it runs across more than ten spreadsheets: your budget, assets, investing, retirement meltdown, stress test, mortgage payoff, Smith Manoeuvre, RESP and more.
Bi-weekly Masterminds
Every two weeks, live and virtual, 90 minutes each: investing one session, side hustles and business the next, with time for your questions.
Every session is recorded. From day one you get 200+ hours of playbacks, plus the full courses: Retirement Masterclass, Stock Investing 101, 6-Figure Job Accelerator and How to Invest in the US.
Some of the sessions so far
10 sessionsInvesting
Investing in the US, with Thomas Lorini
A starter guide to investing in the US
VFV vs VOO: which one to choose
Investing in the Indian stock market
Basics of options trading
Covered call ETFs, explained
Buying the stock market crash
Is the market at a peak?
War, interest rates and investing
Investing through a holding company
6 sessionsRetirement and wealth
Financial planning, with Sam Litchman
Must-dos for a $5M retirement
Being rich vs being wealthy
Infinite banking
How to maximize your RESP
Wills and estate planning
6 sessionsYour mortgage
Pay off your mortgage early?
Mortgage payoff vs investing
The Smith Manoeuvre
Should you switch to a lower rate?
Is it worth breaking your mortgage?
How bond yields move fixed rates
6 sessionsBusiness and side hustles
Start a 6-figure business and quit your job
Quitting your 9 to 5 and building a business
Starting a business: the idea trap
The value equation in business
Building a business with social media
Starting and scaling a business Q&A
5 sessionsCareer and mindset
The power of coaching, with Thomas Lorini
Know your FIGJAM and make millions
Time audits and the power of scheduling
AI tools beyond ChatGPT
Layoffs and workplace rights
Business deep dives at Grow Nation HQ
We have signed an office lease for Grow Nation HQ. It is where we hold in-person events, only for Grow Nation members, for anyone building a side hustle or a business.
The heart of it is the business deep dive: a real, live member business, worked on together in the room, one problem at a time. The goal is to turn a side hustle into a full-time business, and then scale it to seven figures.
Our in-person events in 2025. With our own HQ, they will happen far more often.
7-Figure Business Accelerator
From finding a business idea to your first leads and first dollar, then to six and seven figures. For many members, this is the reason they join.
Four modules, 17 chapters and a partnership track with Navjot, at your own pace.
Module 1Foundation
How to Skip the 9 to 5
The High Leverage Mindset
Your Business Needs Sales, Not Symmetry
Finding the $1M Idea
Idea Validation
Avoiding the Idea Trap
Pre-selling Before You Build
Module 2Offer Creation & Positioning
The Value Equation: Why People Buy Anything
The Offer Framework: Guarantees & Bonuses
Business Canvas: The 9 Pillars of a Business
Pricing Psychology & Offer Math
Scarcity: The Value Amplifier
Module 3Execution & Market Domination
The Growth Engine Blueprint
Building a Perfect Sales Funnel
Nailing the Sales Cycle
The ‘Authority Hacking’ Method
Module 4Road to $1M
The Last Chapter: Systems & Scale
The Partnership Track with Navjot
WhatsApp community
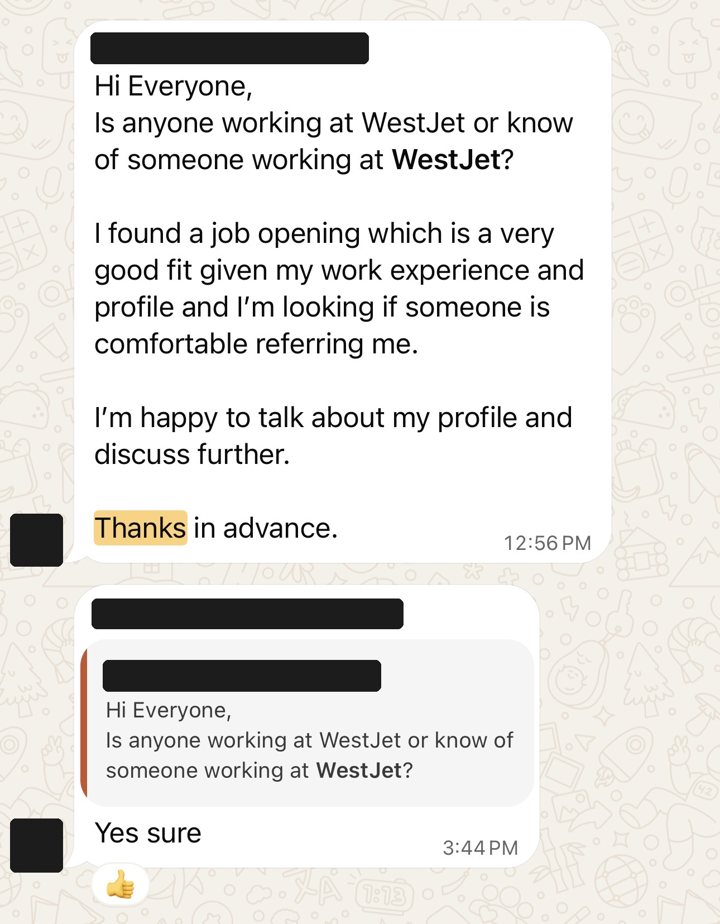
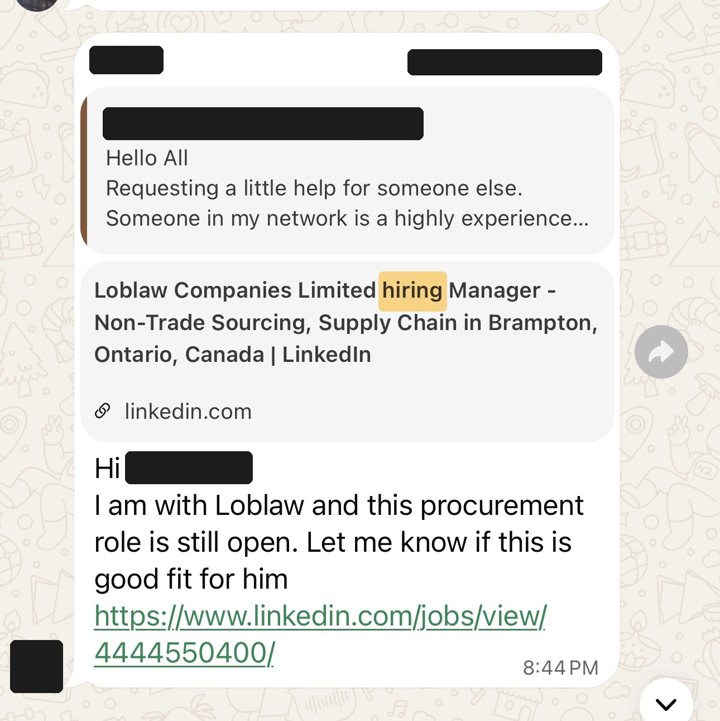
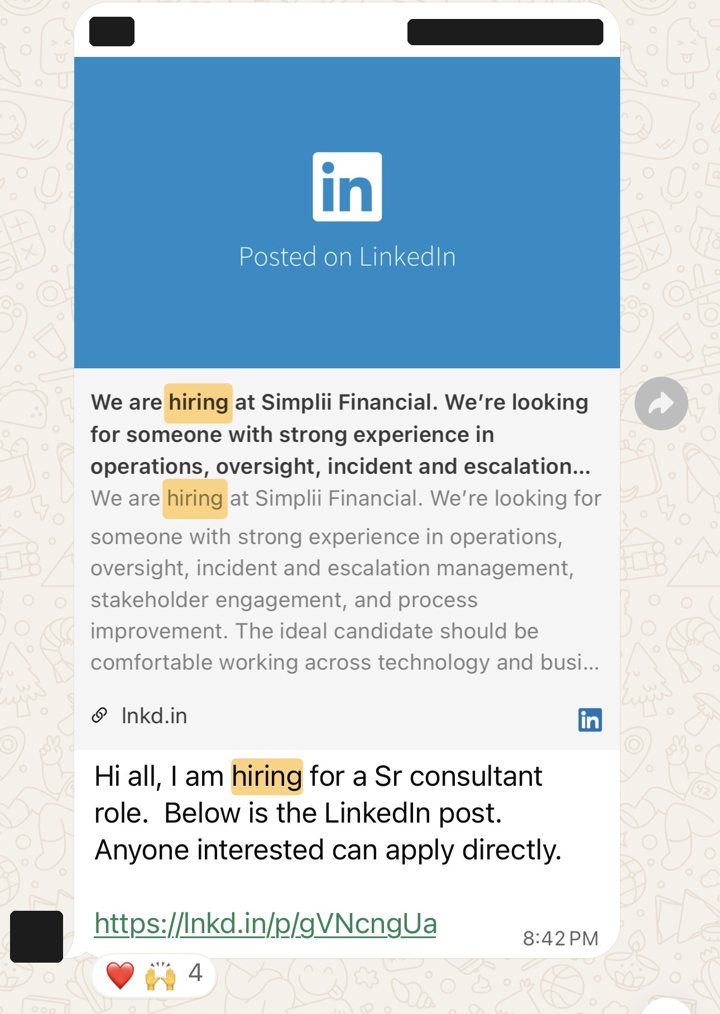
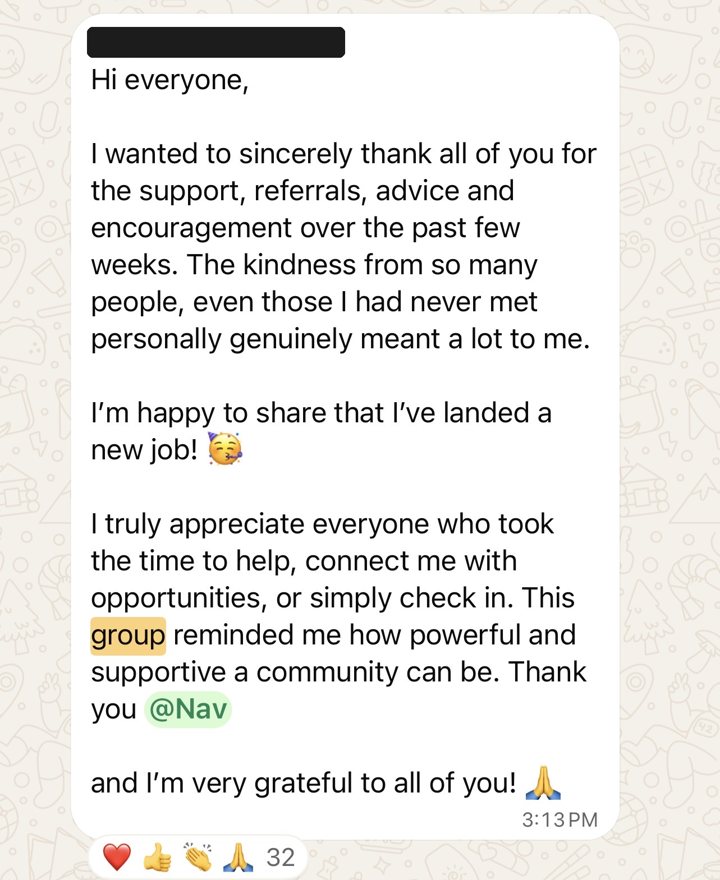
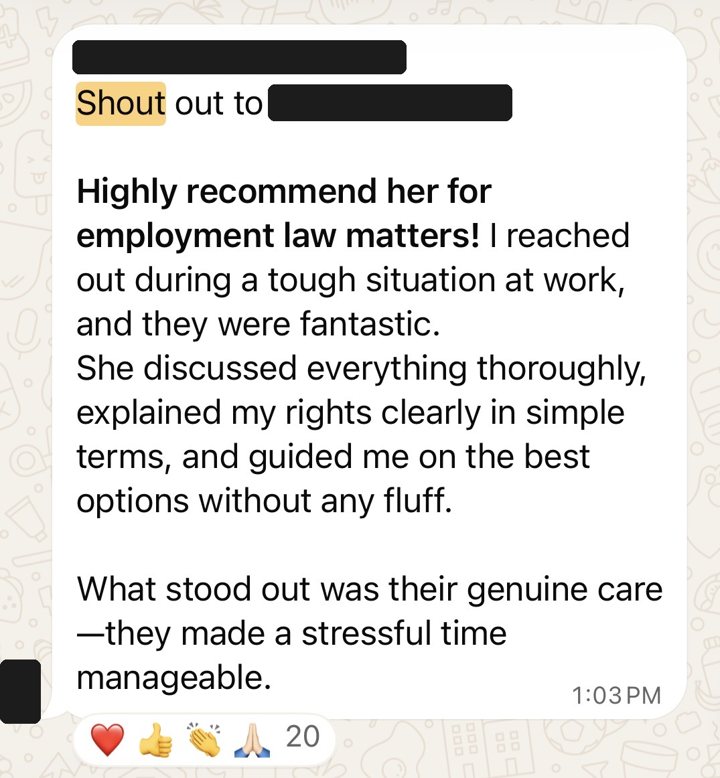
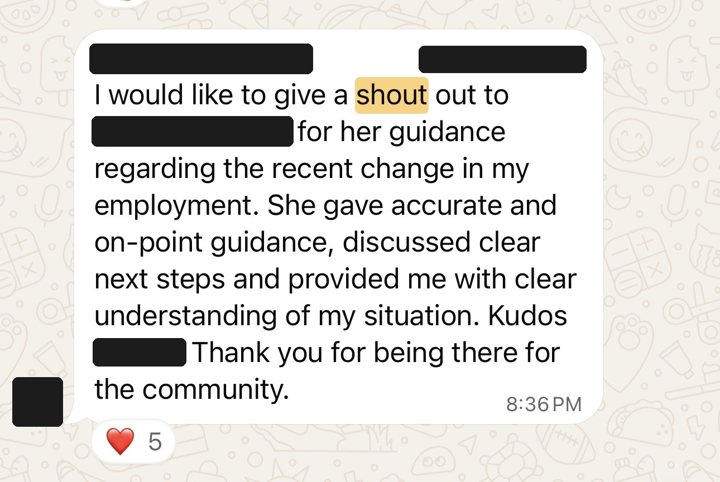
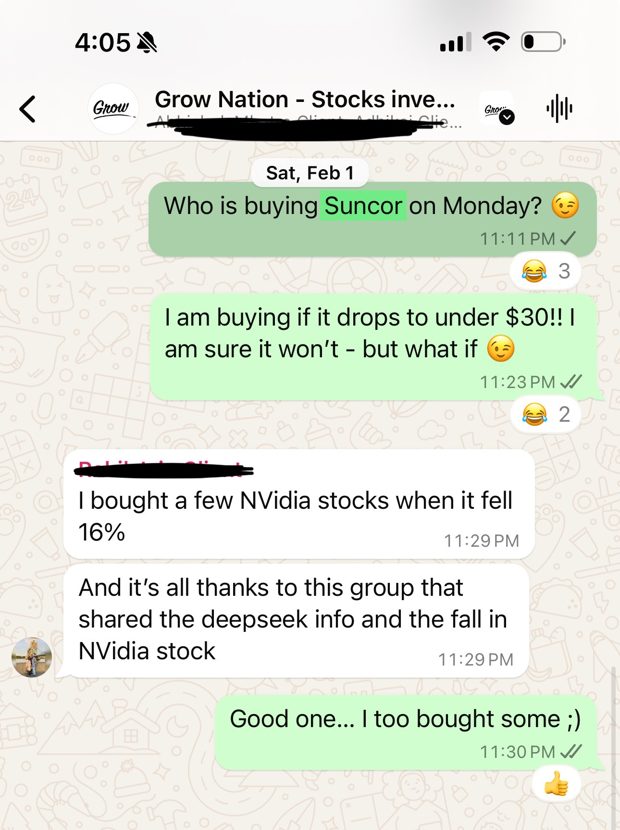
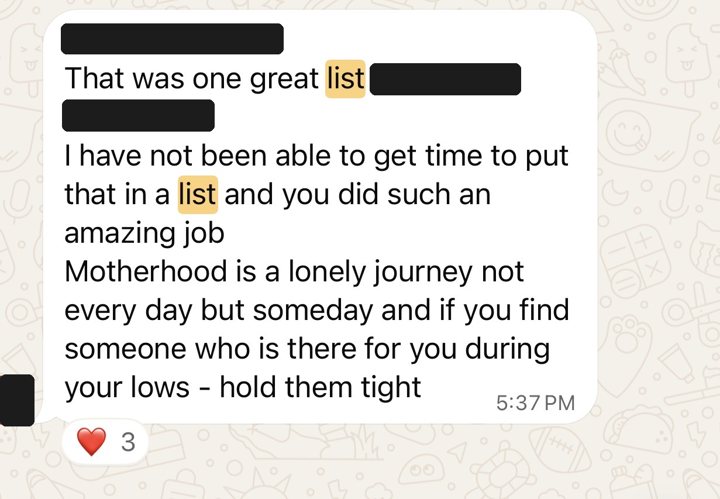
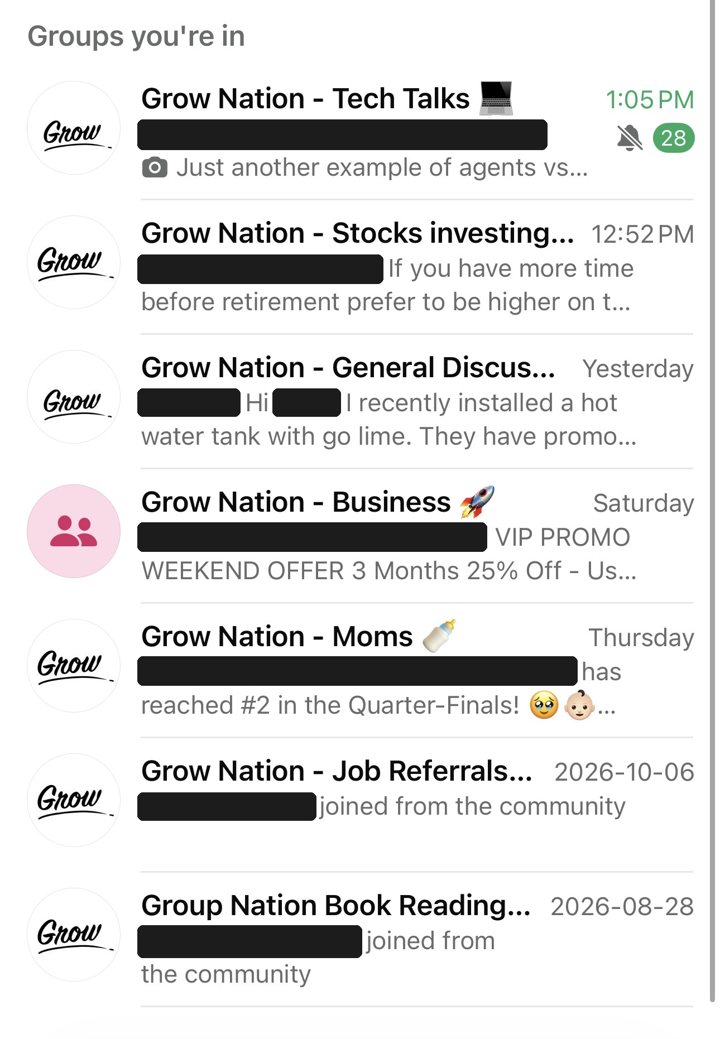
Not small talk. Real people helping each other with real things: jobs, money, business and family.
700+members
Hundredsof companies where members work, so a referral is usually one message away
7rooms
Job referrals
Members post openings at their own companies and refer each other.
Expert help
Lawyers, accountants and specialists in the group help other members.
Investing and everyday life
From the stocks room to a hard day as a new mom.
Real screenshots from the community, with names and numbers blacked out. Tap one to see it full size.
What it costs
1:1 Financial Plan
$2,250
Grow Nation membership, five years$129 a month
$7,740
Total
$9,990
For Grow With Nav mortgage clients
$0
For life. Not one year, not five. Close your purchase, renewal or refinance with us and you keep it all for life. And you still get the best rate, because we shop every lender for your file.
What it’s worth
Retire 5 to 10 years sooner
That is what a good plan does. Families who build their plan with Navjot regularly move their retirement 5 to 10 years earlier and retire with $1 million or more in extra assets. Nothing changes but the plan.
5–10 yearssooner to retirement
$1M+more in assets when you get there
From real plans
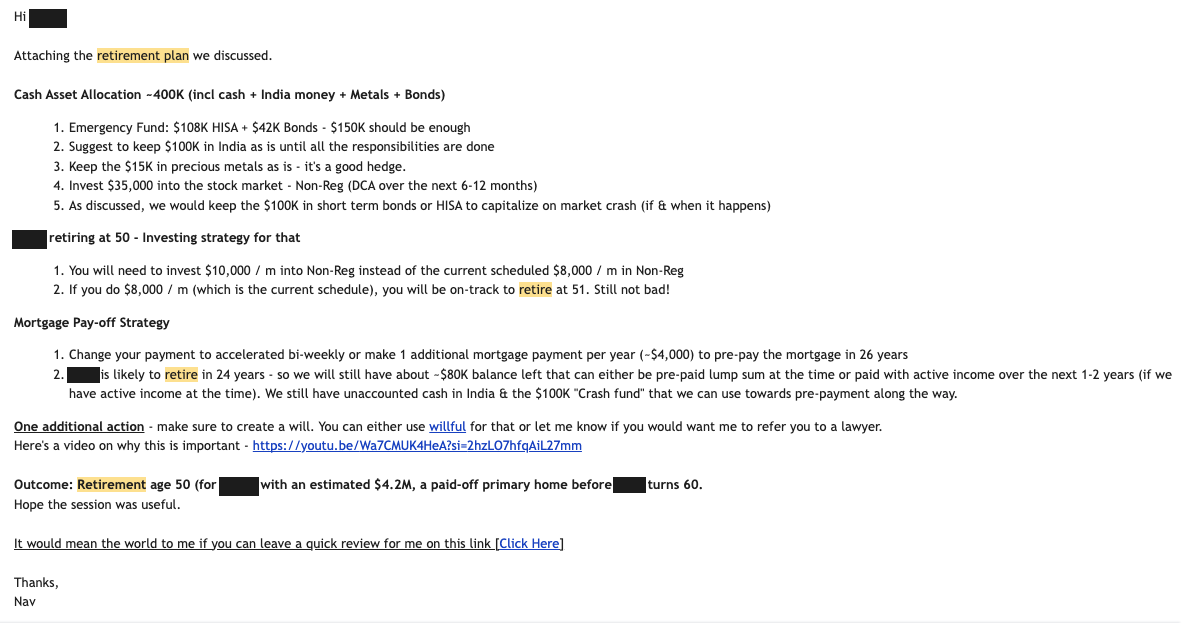
The email this family got after their session: retire at 50, not 60. Names blacked out.
“Buying a new home is always an exciting milestone, but it often comes with its fair share of challenges. The Grow With Nav team made this journey smooth and stress-free by explaining the mortgage process clearly and efficiently at every step.
The other biggest advantage of working with Grow With Nav was having the entire team under one roof (mortgage, realtor, and lawyer all working in sync). This meant we never had to worry about coordination or missed details. Communication was seamless, transparent, and timely, with every minute detail clearly explained and shared with us.
Beyond the home buying process, becoming a member of Grow Nation has been equally rewarding. We now have access to valuable insights and guidance on areas such as retirement planning, business acceleration, and overall financial growth, which adds long-term value well beyond just purchasing a home.
We are extremely happy with our decision to go with Grow With Nav and would highly recommend them to anyone looking for a well-guided, holistic, and trustworthy home-buying experience.”
An educational estimate, not financial, tax or mortgage advice. The stress test replays one period of market history. The future will be different, and it could be better or worse.
Invest every month to start, rising each yearRent Own